A declined application from a bank or an online lender is not the final word on whether your business can get finance. Martin Mackenzie explains why, and what twenty years of banking experience means when a computer has said no.
Photo by Kai Pilger on Unsplash
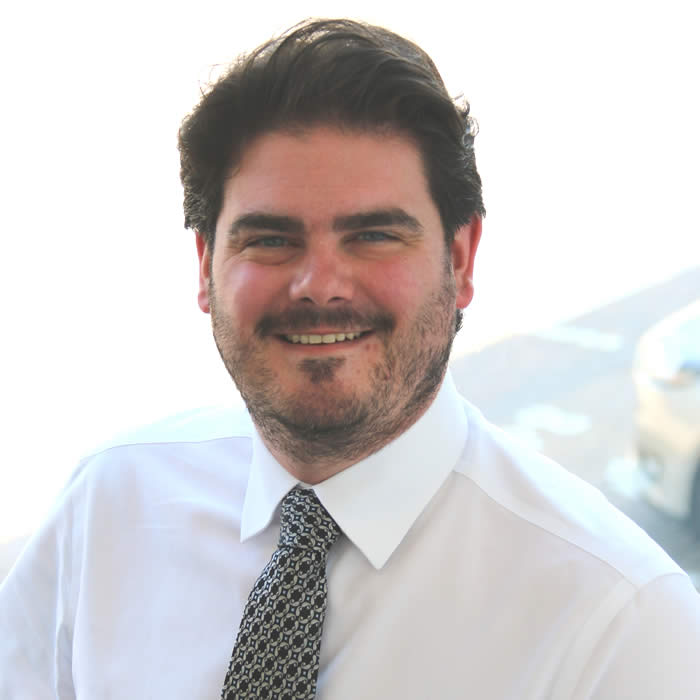
My name is Martin Mackenzie and I am a Director of Mackenzie Commercial Finance Ltd. I have spent twenty years working in banking and finance, starting at Bank of Scotland in the mid 2000s and progressing through business banking and asset finance, including a significant period with Close Brothers Asset Finance where I worked across Scotland as part of their asset finance team. Alana and I set up Mackenzie Commercial Finance in 2026 to provide a specialist asset finance brokerage for Scottish businesses, built on genuine banking experience rather than a three-week sales induction. We are based in Inverness and we cover the whole of Scotland. Our number is 01463 652 653.
This article is about something I have watched happen gradually throughout my career, and which I think matters more to businesses now than it ever has. It is about the difference between a computer making a decision about your finance and a human being making one.
Where it started
When I began my career at Bank of Scotland in the mid 2000s, the branch manager still held meaningful authority over lending decisions. The computer said yes or no, but that was not the end of the conversation. A bank employee could escalate to an underwriting team. The branch manager still had limits within which they could work, and they could apply judgement. They knew the customer. They understood the local business community. They could read between the lines of a set of accounts and recognise a business going through a temporary difficult period versus one heading for serious trouble.
That world has largely gone from personal banking, and it is retreating fast from business banking too. The progress of automation over the past two decades has been significant, and in some ways genuinely useful. In my own banking app today I can open an account, apply for a credit card, transfer a balance, set up a loan, check my business account and pay in a cheque. Almost everything that required a branch visit twenty years ago can now be done in seconds on a phone. For straightforward personal finance requirements, that is a genuine improvement.
But for businesses, it is a different story.
Why automation does not work well for business finance
A personal consumer wanting a loan can enter their name, address, income and the amount they want, and an algorithm returns a decision in seconds. The variables are limited and well-understood. The data is reasonably current. The model works.
Try to do the same with a business and the variables multiply quickly. A set of accounts filed at Companies House eighteen months ago tells you something about where a business was, not where it is today. A business that has been growing strongly for the past year looks very different from its most recent filing. A business that has had a difficult six months looks very different too, and in the latter case an automated system that simply reads the numbers and reaches a conclusion is going to miss the context entirely.
From my experience in asset finance, there are cases where automation works well. A new vehicle for an established business with multiple years of strong filed accounts, borrowing well within its net worth, purchased from a reputable dealer: yes, many of our lenders will provide an automated acceptance for that. But that is the exception. Most of the interesting cases, the ones where a good broker actually adds value, are the ones that do not fit the automated model.
What we do differently at Mackenzie Commercial Finance
At Mackenzie Commercial Finance, we work manually. We get to know the customer and the business. We understand the current position, not just what the accounts show. We understand the story, the trajectory, the reason for the finance requirement and where the business is heading.
We then take that understanding and convey it to the right lender, presented in a way that gives the application the best chance of success. After twenty years working in banking, including time working directly with credit underwriting teams, I know what lenders need to see and how to present a case that gives the underwriter the confidence to say yes. That is not something a broker who has been in the industry for two years can do, and it is not something an algorithm can do at all.
We work with lenders at every position in the market. From the tier-one funders who offer the sharpest rates for the cleanest applications, through to specialist lenders who are specifically set up to look at cases that others will not touch. We have lenders who will consider new-start businesses yet to complete their first year of trading. We have lenders who will look at businesses with a difficult credit history and ask what happened, rather than simply registering a decline. We have lenders who will consider older assets, unusual assets, private sale purchases and complex refinancing requirements.
If the computer has said no, do not stop there
One of the most common conversations I have is with a business owner who has already been declined. They approached their bank. The bank said no. Or they applied online somewhere and the automated system returned a decline. They have concluded that finance is not available to them.
In a significant number of these cases, that conclusion is wrong.
A decline from one lender, or from an automated system, is not a verdict on whether finance is possible. It is a verdict on whether that particular lender, with that particular set of criteria, wants to lend to that business in that circumstance. Across a panel of over 120 lenders, the criteria vary enormously. What one lender will not touch, another will consider as a standard case.
We love to speak to businesses that have been declined elsewhere. We love to speak to businesses that expect they will be declined and have not yet tried. We are paid a commission by the lender on successful completion, which means that asking us to look at a case that has already been declined costs the business nothing if we are not able to find a solution. If we can find one, we earn a commission, and we disclose that commission in full before anything is signed. It is a straightforward arrangement that we are happy to explain in detail to any customer before they commit to anything.
The businesses we work with
Over twenty years in banking and asset finance I have worked with businesses at every stage of the journey. New-start businesses where the limited company has not yet been registered. Established businesses making their first expansion. Family businesses in their third or fourth generation needing full financial restructuring to continue. Businesses going through a difficult period that need someone who understands their situation and can present it to a lender who will listen.
We have a strong focus on traditional asset finance industries. Haulage and transport. Taxi and private hire. Construction and civil engineering. Coach and minibus operators. Plant hire. Manufacturing and engineering. These are industries where assets are central to the business and where asset finance has been a core part of how businesses operate for decades. We understand these industries from years of direct experience, and we have the lender relationships to match.
We are not looking for the simplest cases. We are not looking to compete purely on price with online comparison tools. We are looking for businesses that value the input of someone who has spent two decades understanding how lenders think, and who will take the time to understand what the business needs and find the right solution for it. Whether that is a hire purchase agreement for a new vehicle, refinancing an existing fleet, releasing equity from owned assets, or arranging finance for a start-up, we want to understand the business first and then find the finance that fits it.
Do not let a computer make your final decision
If you have been declined for finance, or if you think you might be, speak to us before you give up. The automated decision that came back from a bank or an online platform is not the last word on what is available to you.
Martin will take the time to understand your situation, identify which lenders on our panel are most likely to look favourably at your case, and present it in the strongest possible light. If we cannot find a solution, we will tell you honestly and we will not have charged you anything for trying. If we can find one, you will have the finance you need and a broker who can continue to support the business as it grows.
Mackenzie Commercial Finance. Asset finance and refinance for Scottish businesses. Based in Inverness. Covering the whole of Scotland. Available at 01463 652 653 at any time. We will visit you in person, at your business premises, your home or anywhere else that suits. There is no charge for an initial conversation and no obligation to proceed.
Our services: Asset Finance including Hire Purchase and Leasing, Asset Refinance and Equity Release, and Business Loans. Arranged for businesses across Scotland from Shetland to the Borders, from Fraserburgh to Oban, from Caithness to Glasgow and everywhere in between.
The views expressed in this article are the personal opinions of Martin Mackenzie as an individual and do not represent the views of Mackenzie Commercial Finance Ltd or Crystal Business Finance Ltd. Nothing in this article should be taken as financial advice or a recommendation. Where this article refers to commercial finance, it refers to unregulated commercial lending which falls outside the scope of FCA consumer credit regulation. Regulated finance for sole traders and partnerships is handled separately and in full compliance with FCA requirements. Mackenzie Commercial Finance Ltd is an Appointed Representative of Crystal Business Finance Ltd, which is authorised and regulated by the Financial Conduct Authority. We are a broker, not a lender. We will receive a commission from the lender for all completed agreements.